Orlando, Florida Nightclub and Bar Insurance
8:30am - 5:00pm Mon-Fri
Will Reply in 15min*
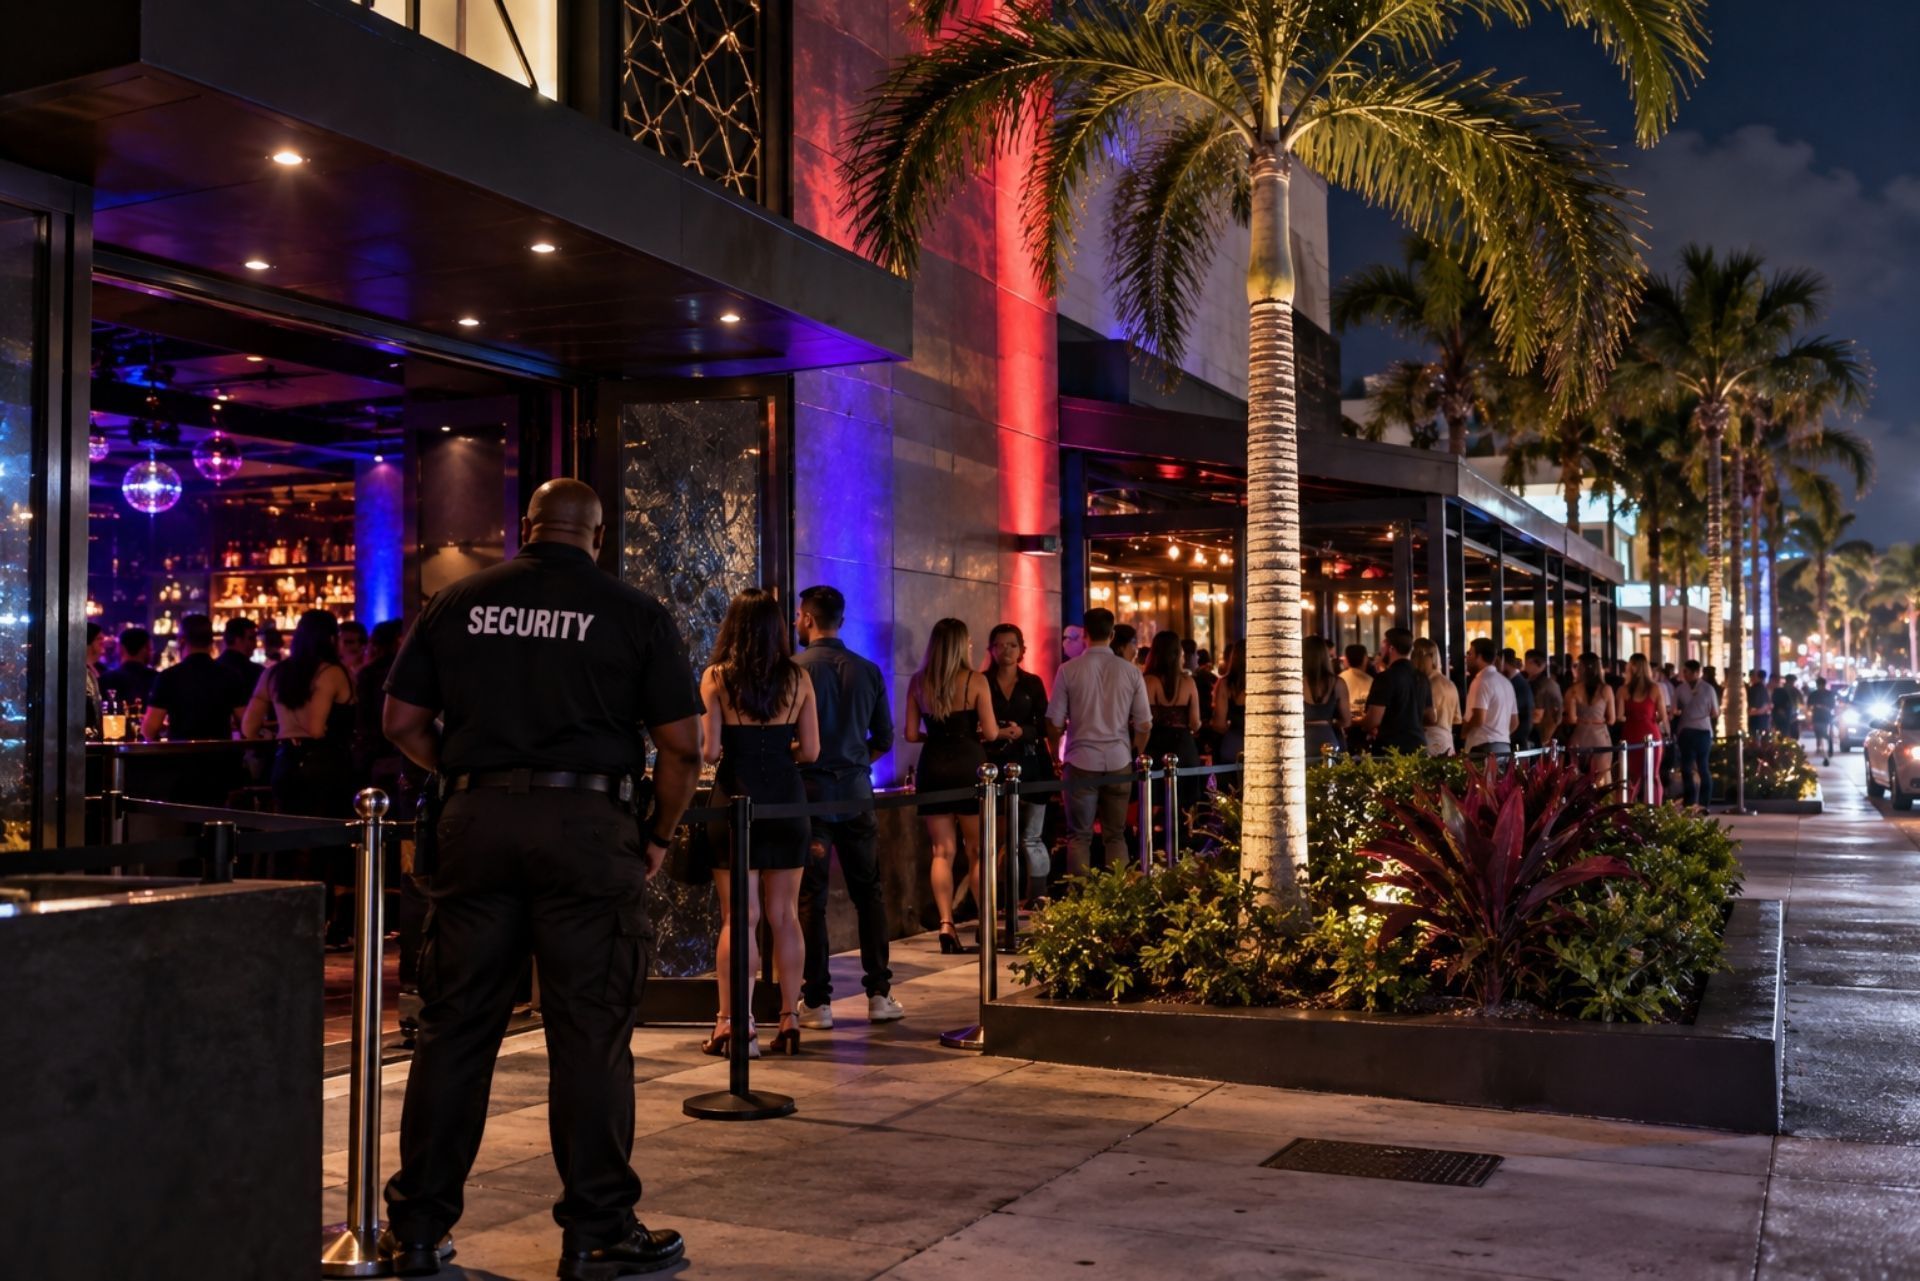
Orlando's International Drive corridor, downtown entertainment district, and surrounding nightlife zones draw millions of visitors each year, and the venues that serve them face a risk profile unlike almost any other business. A single night can involve thousands of patrons, flowing alcohol, live DJs, pyrotechnics, and packed dance floors where tempers occasionally flare. If you own or operate a
nightclub or bar in Orlando, your insurance program needs to account for liquor liability, assault and battery exposures,
property damage from storms, and the specialized equipment that keeps the party going. The stakes are high: one uninsured claim can wipe out years of profit and put your liquor license at risk. This guide breaks down the specific coverages, cost factors, and risk management strategies that matter most for Orlando venue owners in 2026.
Orlando isn't just a theme park town. The city's nightlife economy generates hundreds of millions in annual revenue, and that volume of late-night activity creates a concentrated risk environment. Florida's dram shop laws hold alcohol-serving establishments liable when they serve a visibly intoxicated person or a minor who then causes harm. That legal exposure, combined with the state's hurricane risk and a dense tourist population unfamiliar with local roads, makes insuring a nightclub here more complex than in most U.S. markets.
Florida's 2023 tort reform under HB 837 did shift some dynamics in your favor. The law shortened the statute of limitations for negligence claims from four years to two and modified comparative fault rules, which has helped stabilize some liability premiums. Still, nightclubs and bars remain a class that most standard carriers won't touch. You'll typically need a surplus lines or specialty insurer, and working with a broker who understands Florida's hospitality market is not optional: it's a prerequisite.
The 2026 market is showing some positive signals.
Commercial property insurance rates in Orlando are
trending flat to 5% lower, with claims-free properties seeing meaningful premium reductions. That said,
liability lines for nightlife venues remain firm, and carriers are scrutinizing security protocols more closely than ever.
By: AJ Leibell
President of Bellken Insurance Group
Core Coverage: Liquor Liability and General Liability
Your general liability policy is the foundation, but for any venue that derives significant revenue from alcohol sales, it's only half the equation. These two coverages work together, but they protect against different types of claims.
Liquor Liability: Protecting Against Alcohol-Related Incidents
Florida's dram shop statute (F.S. 768.125) creates direct liability for establishments that serve alcohol to minors or to persons "habitually addicted" to alcohol. A patron who leaves your bar intoxicated, causes a car accident, and injures a family of four can generate a claim that reaches seven figures fast. Your general liability policy explicitly excludes alcohol-related claims, which is why a standalone liquor liability policy is essential.
Typical liquor liability limits for Orlando nightclubs start at $1 million per occurrence with a $2 million aggregate, though high-volume venues on I-Drive or in the downtown core often carry $3 million to $5 million in coverage. Premiums for a mid-sized bar can range from $4,000 to $15,000 annually, depending on revenue, hours of operation, and claims history. Nightclubs with late-night hours and high per-capita alcohol sales will land at the upper end or beyond.
One common mistake we see: owners assume their liquor liability policy covers incidents that happen in the parking lot or on the sidewalk outside. Check your policy territory carefully. If your venue has a patio, valet area, or outdoor queue, make sure those spaces are included.
Assault and Battery Coverage: Essential for Security Risks
Standard general liability policies almost always exclude assault and battery claims. This is a problem for nightclubs, where altercations between patrons, or between security staff and patrons, represent one of the most frequent and expensive claim types. A bouncer who uses excessive force removing a patron can trigger a lawsuit that your GL policy won't cover at all.
Assault and battery coverage is typically added as an endorsement or purchased through a separate specialty policy. Limits of $100,000 to $500,000 per occurrence are common, though some carriers offer up to $1 million. Premiums depend heavily on your venue's capacity, whether you employ armed security, your incident history, and the training credentials of your door staff.
Picture this: a patron is struck by another guest on your dance floor, suffers a concussion, and racks up $40,000 in medical bills plus lost wages. Without assault and battery coverage, you're paying that out of pocket, even if your staff did nothing wrong. This coverage fills a gap that can otherwise bankrupt a venue.
Protecting Your Physical Assets and Entertainment Equipment
Your building, its contents, and your specialized entertainment gear represent a significant capital investment. A single hurricane, electrical fire, or water main break can shut you down for weeks or months.
Commercial Property and Tenant Improvements
Most Orlando nightclub operators lease their space rather than own it, which means tenant improvement coverage is critical. You've likely invested $200,000 to $1 million or more in buildouts: custom bars, VIP sections, acoustic treatments, dance floors, and restroom upgrades. If a fire destroys those improvements, your landlord's policy won't reimburse you for any of it.
Your commercial property policy should cover the building (if you own it), your tenant improvements, furniture, fixtures, inventory, and business income lost during a covered shutdown. In hurricane-prone Central Florida, pay close attention to your wind and named storm deductibles. These are often set as a percentage of the insured value (typically 2% to 5%), not a flat dollar amount, so a $1 million property could carry a $50,000 wind deductible.
Specialized Entertainment Exposures: Sound, Lighting, and DJs
A nightclub's sound system, LED walls, laser rigs, fog machines, and DJ equipment can easily represent $100,000 to $500,000 in value. Standard property policies may cap coverage for electronic equipment or exclude items that are rented, leased, or owned by third-party performers. If a touring DJ brings a $30,000 setup and it's damaged by a sprinkler malfunction in your venue, you could be liable.
Inland marine or equipment floater policies fill this gap. They cover portable electronics, sound and lighting rigs, and similar gear on a scheduled or blanket basis. If you host guest DJs or rent equipment for special events, make sure your policy addresses borrowed or rented items, and require visiting performers to carry their own coverage with your venue named as an additional insured.
Comparing Coverage Needs for Orlando Establishments
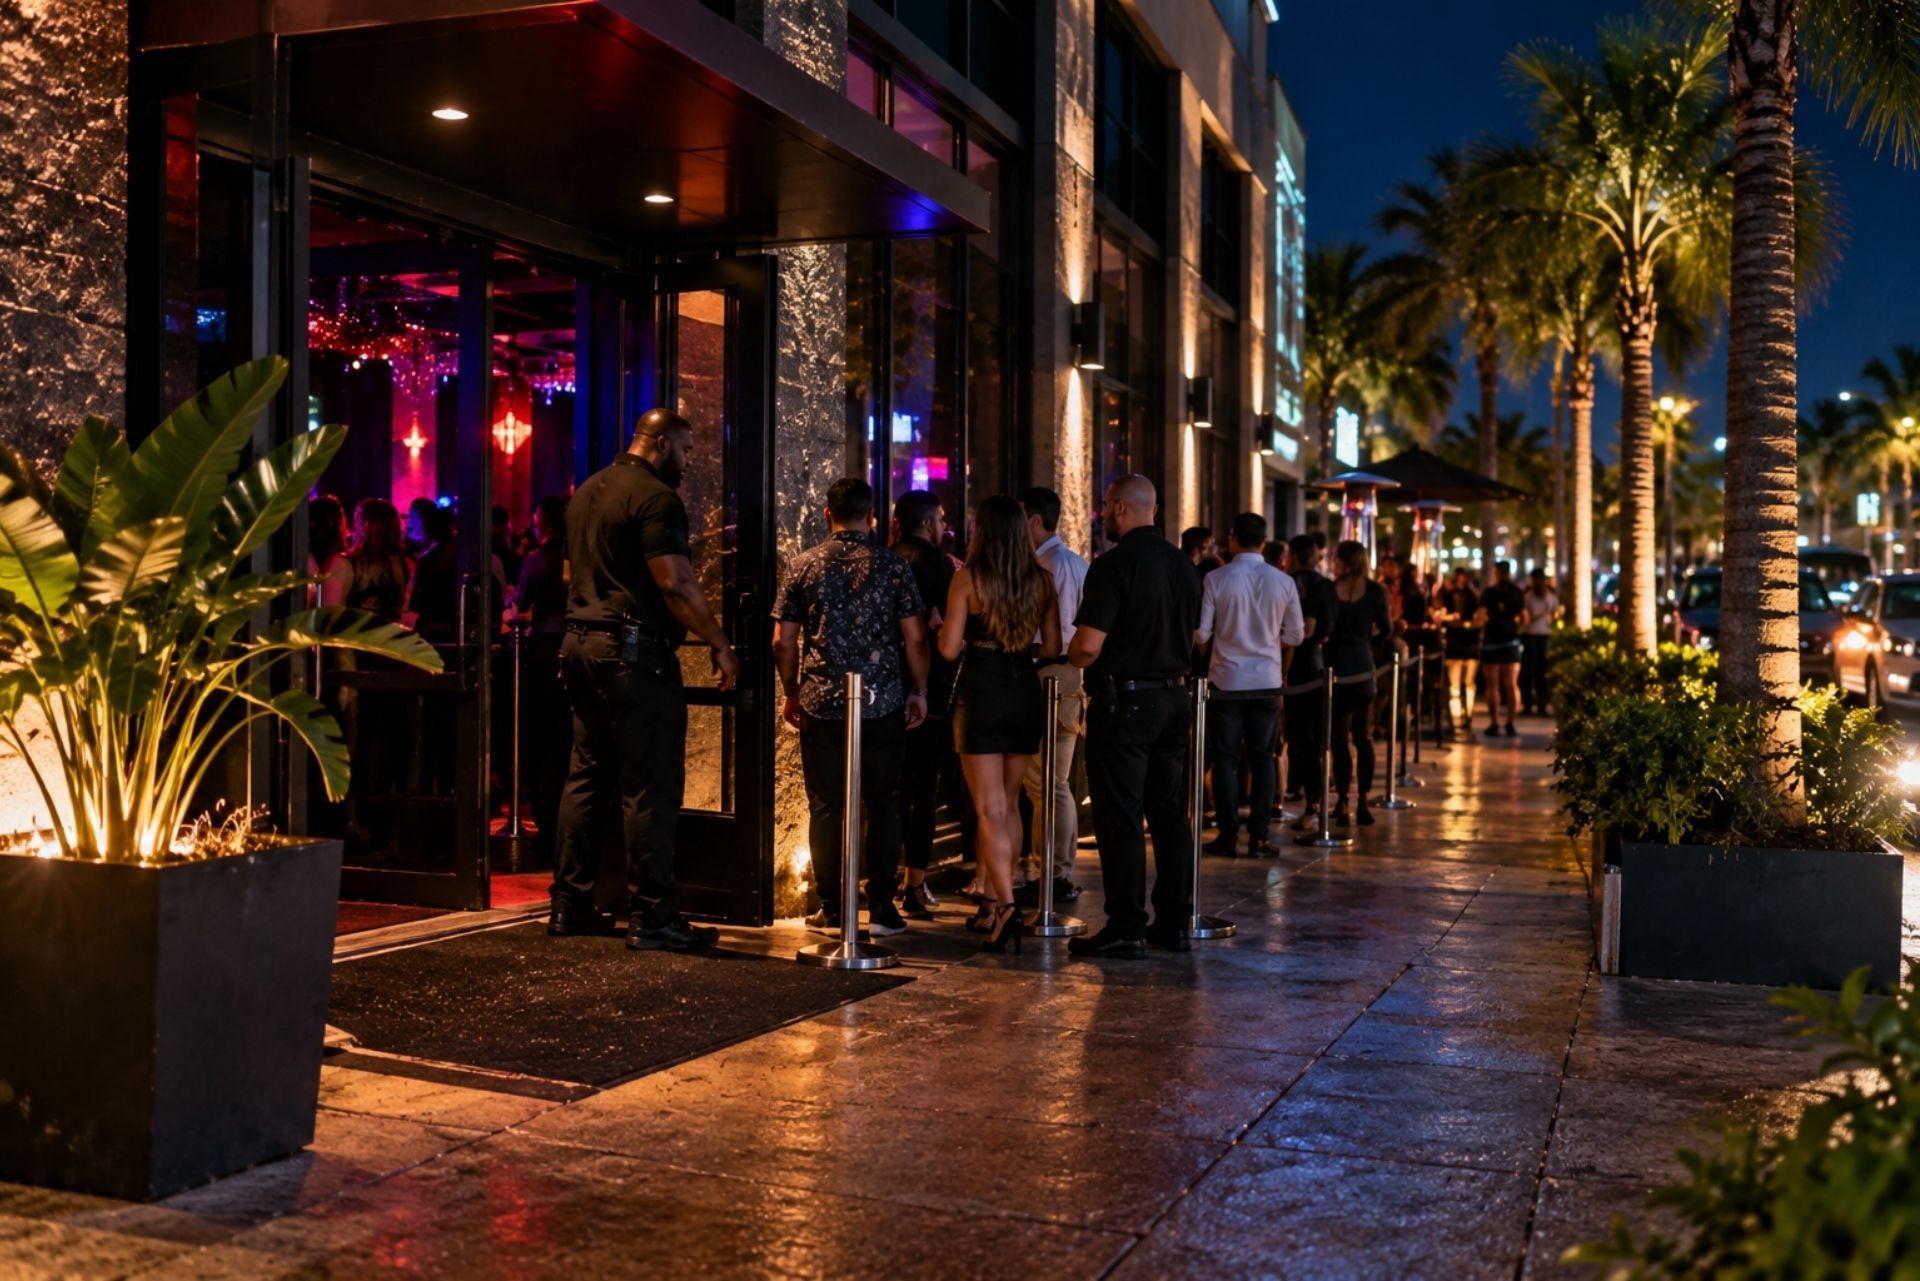
Not every alcohol-serving venue faces the same risk profile. A craft cocktail lounge with 80 seats and a midnight closing time has very different exposures than a 1,500-capacity nightclub open until 4 a.m. Here's a quick comparison:
| Coverage Type | Neighborhood Bar | High-Volume Nightclub |
|---|---|---|
| General Liability | $1M/$2M standard | $2M/$4M or higher |
| Liquor Liability | $1M per occurrence | $3M-$5M per occurrence |
| Assault & Battery | $100K-$250K | $500K-$1M |
| Property/Contents | $150K-$500K | $500K-$2M+ |
| Entertainment Equipment | Minimal | $100K-$500K floater |
| Estimated Annual Premium | $8,000-$18,000 | $25,000-$75,000+ |
These figures reflect 2026 Central Florida market conditions. Your actual premiums will vary based on claims history, revenue, and the specific underwriting criteria of your carrier. The hospitality insurance market in 2026 is showing more carrier appetite for well-managed venues, which means competitive options exist if you can demonstrate strong risk controls.
Factors Influencing Insurance Costs in Central Florida
Understanding what drives your premium helps you control it. Two venues on the same block can see wildly different quotes based on a handful of variables.
Venue Size and Annual Revenue Projections
Carriers price nightclub and bar policies based heavily on gross revenue and occupancy capacity. A venue doing $2 million in annual alcohol sales will pay significantly more for liquor liability than one doing $500,000. Your occupancy limit matters too: a 300-person venue presents a different crowd control challenge than one permitted for 1,200.
Revenue projections need to be accurate. If you underreport your expected sales to get a lower premium and then file a claim, the carrier can reduce your payout proportionally. This is called a "coinsurance penalty," and it catches bar owners off guard more often than you'd think. Be honest about your numbers upfront.
Security Protocols and Staff Training Credits
This is where you have real control over your costs. Carriers increasingly offer premium credits of 5% to 15% for venues that implement documented security protocols. These include TIPS or ServSafe alcohol training for all bartenders and servers, written use-of-force policies for security staff, functional ID scanners at every entry point, and interior/exterior camera systems with at least 30 days of footage retention.
Some carriers also look favorably on venues that employ off-duty law enforcement as part of their security team, or that use third-party security firms with their own insurance. The more you can demonstrate a proactive approach to preventing incidents, the more pricing flexibility your broker can find.
Does my general liability policy cover fights between patrons? No. Standard GL policies exclude assault and battery. You need a separate endorsement or standalone policy for those claims.
How much does liquor liability insurance cost for an Orlando bar? Premiums typically range from $4,000 to $15,000 per year for a mid-sized bar. Nightclubs with higher revenue and later hours can pay $20,000 or more.
Am I required to carry liquor liability insurance in Florida? Florida doesn't mandate it by statute, but your landlord, lender, or local licensing authority may require it as a condition of your lease or permit. Operating without it is a serious financial risk regardless.
What happens if a guest DJ's equipment is damaged at my venue? You could be held liable. An inland marine or equipment floater policy can cover this, and you should require guest performers to provide certificates of insurance naming your venue as additional insured.
Does Florida's tort reform (HB 837) affect my premiums? It can. The law's changes to comparative fault and statute of limitations have helped stabilize liability costs for some hospitality businesses, though nightclubs remain a high-risk class.
Will my property policy cover hurricane damage to my sound system? It depends on your policy's equipment sublimits and named storm deductible. Many standard property policies cap electronic equipment coverage, so a separate floater is often necessary.
The Bottom Line for Orlando Venue Owners
Running a nightclub or bar in Orlando means operating in one of the country's most dynamic, and most risk-exposed, entertainment markets. Your insurance program isn't a line item to minimize: it's the financial backbone that keeps your doors open after a bad night. Liquor liability, assault and battery coverage, property protection, and entertainment equipment policies each address a distinct risk that standard business insurance ignores.
The venues that pay the lowest premiums aren't the ones that cut corners on coverage. They're the ones with documented training programs, professional security protocols, and accurate financial reporting. If you haven't reviewed your policies in the last 12 months, now is the time.
If you're opening a new venue or need to reassess your current coverage,
get a quote from a broker who specializes in Florida nightlife risks. The right program protects your investment, your employees, and your ability to keep the music playing.
About The Author:
AJ Leibell
As President of Bellken Insurance Group, I’m dedicated to providing clients with clarity, confidence, and protection through personalized insurance solutions. With years of experience serving individuals and businesses, my focus is on building lasting relationships and ensuring every client receives dependable coverage that fits their goals and budget.
Your Personal Insurance Solutions
Choose Bellken Insurance Today
Choice and Transparency
The independent insurance agents are completely different from the insurance company agents. They work for themselves and not for the company. They sell their own policies to the customers and that is why they are called independent agents.
Your Advocate
Independent agents are more inclined to provide you with the best coverage that is suitable for your needs. They can also help you with your budget and make sure that you get the best coverage at an affordable price.
Lifetime expert advice
Independent insurance agents are insurance experts who have a deep understanding of the industry. They are able to clearly explain complex policies or rate changes, and are well-versed in the inner workings of various insurance companies. With years of experience dealing with multiple insurance providers, they are reliable sources of
Our Testimonials
Hear from our clients

This review goes directly to Aj Leibell. Being foreign is not easy to found people that are willing to help you, he was extremely helpful and had so much patience that I can only be grateful. This company trust me, is the best in customer service and prices.
Francisca Diaz Cortez

On behalf of my mom, who dealt with AJ Leibell to resolve an issue. She would highly recommend this agency due to their professionalism, kindness and going over and above what was necessary.
Jessica Moore

Bayview Tower Condo Association is located in Miami, Florida, we are a community comprise of 36 units. Bellken has been our insurance agent for the last 10 years. During all these years our insurance needs have been met by Bellken in a professional and trustworthy manner. The entire staff is courteous, knowledgeable and attentive to detail.
Bayview Tower

We have used their services for over 17 years and are quite satisfied with the support provided. EH
Ed Hays
REQUEST A QUOTE
Get an insurance quote online today!
Get started today!
Speak directly with a Bellken Insurance specialist today!
Prefer to speak with an agent now?